What Employers Actually Get per Dollar Spent Inside a PEO Administration Fee
A PEO fee bundles services and leaves out premiums, so compare total cost.
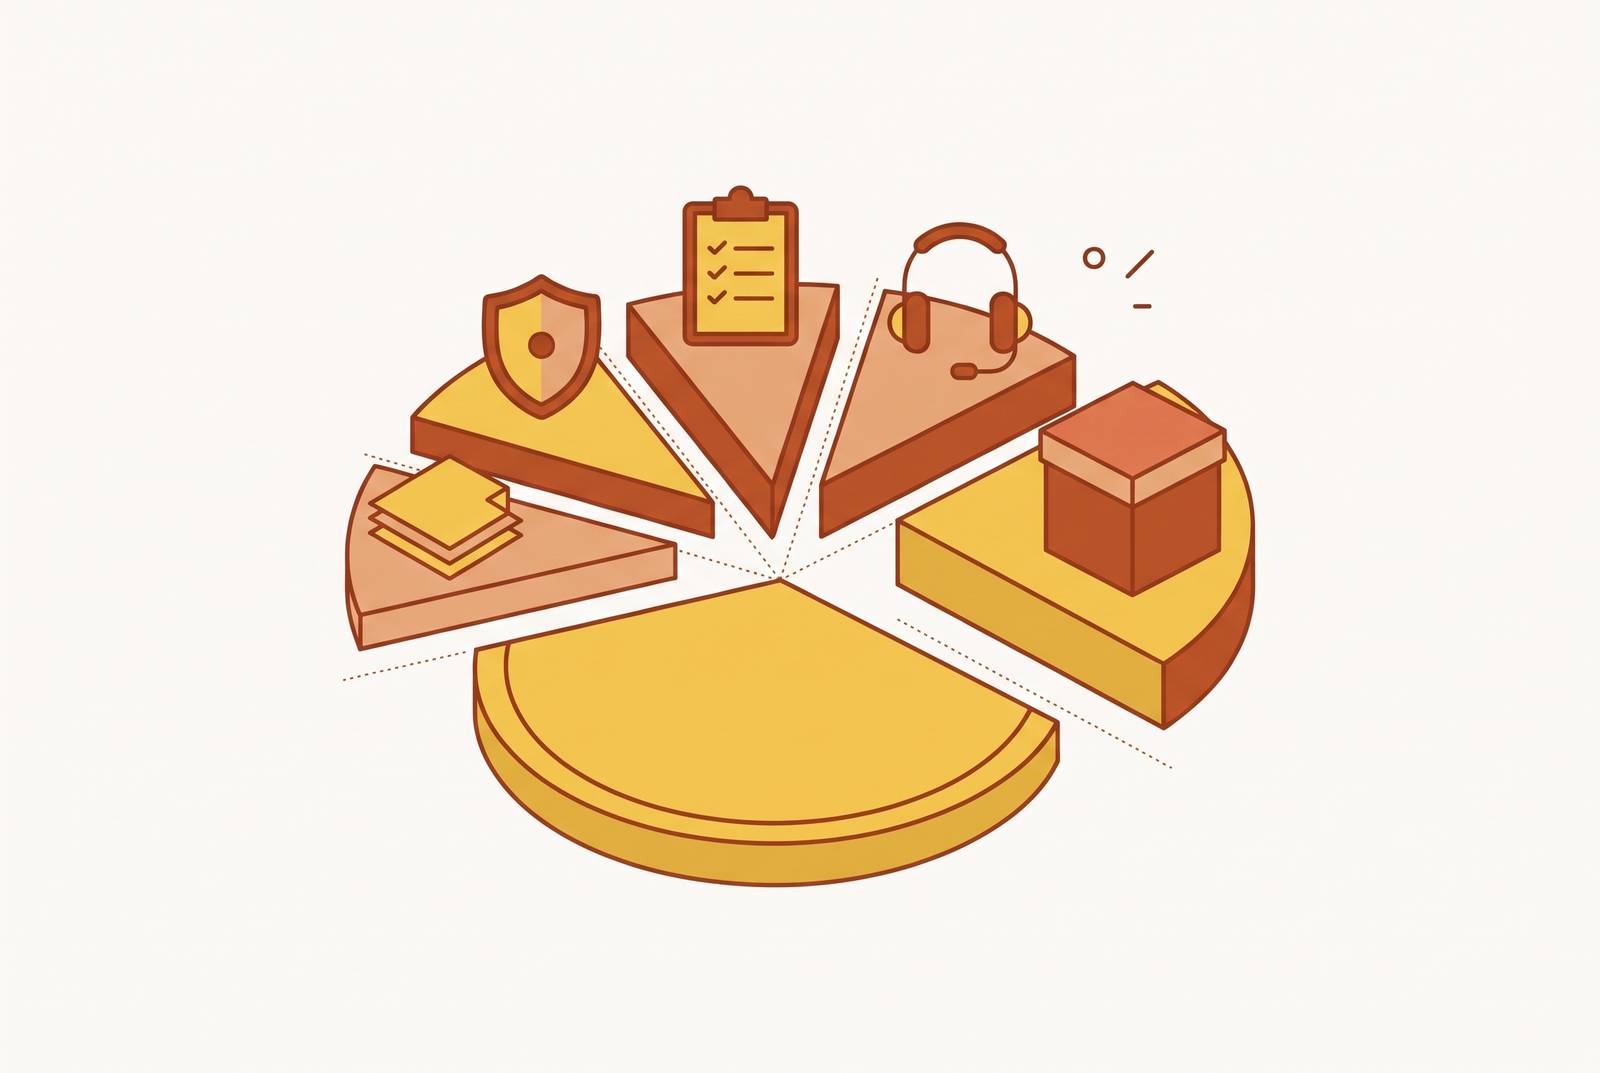
A PEO administration fee buys bundled payroll, benefits administration, compliance support, and HR infrastructure, with insurance premiums and employment taxes charged separately on the invoice. A traditional broker or AI-native benefits platform replaces only the benefits layer of that bundle. A fair per-employee cost comparison therefore weighs the PEO’s total cost against the cost of buying benefits, payroll, and HR services separately, going beyond its admin fee and a broker’s fee alone.
How a PEO invoice is actually structured — and why the admin fee is not the headline number
A founder or CFO receives a clean, one-number PEO proposal and forwards it with the question “is this the cost?” The number may describe only the administration fee. The eventual invoice also includes health premiums, payroll taxes, workers’ compensation, and retirement contributions. Those expenses exist whether the employer uses a PEO or not, although their amounts and administration can differ.
ADP’s 2026 article on PEO costs distinguishes the admin fee from total cost and notes that benefits, workers’ compensation, and additional services often vary more by provider than the fee itself. Two offers with identical per-employee-per-month rates can produce budgets that diverge by tens of thousands of dollars once the other charges are exposed. Pass-through expenses remain costs of employment that the PEO administers.
The two pricing models and what each one actually charges
PEOs primarily price administration per employee per month, or PEPM, or as a percentage of gross payroll. PEPM assigns a flat monthly charge to each active employee, so the fee scales with headcount. It is easy to budget for as staffing changes. PEO Benefit Partners says small teams with high salaries often save more with this model.
With percentage-of-payroll pricing, the fee depends in part on how much employees are paid. Hotaling Insurance identifies the resulting misalignment at renewal, when merit increases raise the PEO’s revenue without expanding its service scope. The administrative work need not change at all. For tech companies with high average salaries, the practical negotiating direction is therefore toward PEPM.
Some proposals use hybrid structures, combining a flat employee charge with a payroll percentage for services such as workers’ compensation. These require the same separation of service fees from insurance costs. The quote also reflects workforce size, industry, employee locations, payroll structure, and compliance complexity. A rate that is the same for everyone needs a closer look because those differences affect the work and risk it pays for.
What the admin fee is supposed to include — and what legitimately sits outside it
PEO Benefit Partners says the core administration services are payroll processing, tax filings and remittance, and the work of producing and delivering year-end W-2 forms. Payroll support should cover the employer’s schedule, whether it is weekly, bi-weekly, semi-monthly, or monthly. The boundary should be explicit in the contract. State unemployment insurance administration, new hire reporting, I-9 compliance, E-Verify where applicable, and multi-state tax registration maintenance also belong within the defined scope.
The same fee should pay for benefits administration and enrollment, access to the HRIS, and basic employee self-service. The fee should also pay for standard HR compliance support, help to develop or review a handbook, and termination support and documentation. A proposal should not present them as included while charging for them again elsewhere.
Insurance premiums sit on the other side of that boundary. Health, dental, vision, life, and disability coverage, class-code-specific workers’ compensation premiums, 401(k) plan administration, and FSA/HSA administration can legitimately appear separately. So can state-specific compliance fees and a negotiable, one-time implementation fee. Workers’ compensation requires particular care because some PEOs bundle it into administration, making their headline fee look higher than an offer that bills it separately. Both amounts are needed for a fair comparison, but health benefits create the most consequential confusion between administration and the cost being administered.
How health benefits sit inside a PEO invoice — and where markups hide
The benefits part of the bill has two separate charges, one for administration and one for the actual premium pass-through. Enrollment and carrier coordination belong to the administrative service. The premium purchases the insurance coverage itself. A PEO can also earn a margin on premiums without showing that margin as a separate line, so a low admin fee does not establish that the benefits arrangement is inexpensive.
The pooled purchasing advantage can nevertheless be substantial. Employers, typically those with under 50 employees, can get large-group pricing through a PEO’s risk pool that they cannot get on their own. For some, that saving alone exceeds the admin fee. As a company grows and develops its own claims experience, however, an independent broker may be able to negotiate comparable or better pricing, reducing the value of the pool.
Because employer health costs are rising substantially year over year, premiums deserve scrutiny at every renewal. Even a small percentage markup spreads across a large expense and the whole workforce. Employers should require disclosure of whether premiums pass through at carrier cost and whether the PEO earns a margin on health or ancillary coverage. Refusal to answer is a warning sign. Plan tiers and contribution strategy also deserve attention because the employer’s payment depends on plan design, funding choices, and the carrier’s rate.
The compliance services embedded in the admin fee — and what they actually cover
For multi-state payroll, the PEO registers as employer of record for payroll tax purposes and handles withholding, SUTA filings, and new hire reporting across jurisdictions. Even one remote employee can create nexus and filing obligations. Registration windows after first wages are paid can be narrow, while workplace posting requirements change with wage and leave laws. This administrative work continues beyond the initial setup.
The ACA employer mandate still turns on the client’s workforce. It applies at 50 or more full-time-equivalent employees, and using a PEO does not remove that test. The PEO administers coverage offers on the client’s behalf. Its filing work reduces operational risk, but the employer remains responsible for the coverage decision.
Plan compliance also extends beyond offering insurance. Calendar-year Form 5500 filings are normally due through the Department of Labor’s EFAST2 system by July 31 of the following year, and plans that file late risk civil penalties and an audit. COBRA administration includes timely notices, eligibility and election-period tracking, and premium processing. Errors here can trigger Department of Labor and IRS penalties.
A PEO that sponsors health and retirement plans takes on major fiduciary responsibilities, while the client usually still has to monitor the provider and, without a 3(38) investment manager, the 401(k) investments. The co-employment agreement should delineate those duties. The fee purchases execution and support, while the employer remains responsible for its decisions.
At what company size and growth stage the admin fee delivers positive ROI — and when it stops
For companies under 50 employees, pooled benefits pricing, bundled compliance infrastructure, and consolidated vendor relationships can cost less than assembling equivalent services independently. The comparison also counts the cost of having HR staff in-house, which could include even one experienced HR manager. The small-company case is therefore structurally sound. Its strength depends on what the employer would otherwise need to purchase and manage.
The calculation changes as headcount, payroll, and claims experience grow. Pooling is worth less, while percentage-based administration charges rise with pay and the company gets data it can use to negotiate on its own. Series B and growth-stage investors look at how these costs change when they model headcount. An unbenchmarked PEO fee becomes an unexamined assumption in that model.
Tax treatment and contract terms can complicate the decision. Joining or leaving a non-certified PEO mid-year can reset some tax wage-base calculations, but IRS-certified CPEOs avoid this problem. Contracts usually last 12–24 months, often with automatic renewal and large penalties for leaving early. January 1 is the cleanest transition date, while a mid-year exit involving withholding resets can disrupt employees’ wages.
Platform setup, internal labor, and payroll cleanup must also enter the savings case. There is no universal headcount at which departure becomes correct. The relevant comparison is total PEO cost against a dedicated broker, standalone payroll, and the HRIS the company already uses. That comparison requires identifying which services the alternatives actually replace.
What does a PEO cost per employee versus a broker or AI-native model?
A PEO’s per-employee administration charge pays for more than benefits access. Payroll processing, tax filing, workers’ compensation administration, multi-state registration, and HRIS infrastructure are substantive parts of the bundle. A benefits broker does not replace them all. Comparing the PEO’s PEPM charge with a broker’s compensation without pricing replacement infrastructure understates the alternative’s cost.
A dedicated broker instead provides plan selection across carriers without being tied to the PEO’s preferred relationships, renewal negotiation, and direct carrier relationships for the employer. There is no co-employment arrangement, and the employer retains plan control. Compensation still deserves examination in this model. Traditional brokers are structurally paid by carriers, and that arrangement can limit the incentive to seek a better-priced plan at each renewal.
The emerging AI-native brokerage model adds analysis across carrier and workforce data, automated compliance monitoring across jurisdictions, and around-the-clock employee support. It can provide benefits services without the overhead of co-employment or a per-employee administration fee. That does not make the whole operating model free. An employer leaving a PEO still needs payroll and HR infrastructure, including support for its state footprint.
ICHRA offers a different benefits structure rather than another way to purchase the same group plan. The employer gives employees a fixed monthly allowance to buy individual coverage, so the employer knows how much it will pay and employees can choose their plans. It is not generally available through traditional PEO arrangements, although a small number have begun offering it.
Hotaling’s evaluation framework asks whether a dedicated broker can give the employer access to similar benefits with more control. For employers that have outgrown pooling, that model can win on total cost. The savings still have to justify the transition effort.
How to read a PEO proposal and benchmark the admin fee against what it actually delivers
Before the next renewal, an operator evaluating a first PEO or reconsidering an existing arrangement should build one cost view covering every recurring and usage-based charge. Medical, dental, vision, retirement administration, workers’ compensation, unemployment costs, platform fees, and one-time charges should appear separately. Premium margins need explicit disclosure as well. Only then can the administration fee be compared with the services it purchases.
The proposal’s internal consistency is the first test. Payroll processing, tax filings, benefits enrollment, and HRIS access should not reappear as extra charges if the stated fee includes them. An unusually low admin quote is a reason to look closely at benefit spreads. Uncapped annual escalators, undisclosed premium margins, and restrictive automatic renewals are additional reasons to question the offer before signing.
PEO Benefit Partners identifies administration reductions of eight to fifteen percent as common when competitive quotes are presented, though reductions are not guaranteed. Benefit rate increase caps and cleaner exit provisions are also negotiable. Implementation fees may be waived for committed headcount growth projections, while employers with clean workers’ compensation loss histories should ask how the experience modifier benefits their price.
The final comparison should use the same headcount, state footprint, and benefits setup for each model. It should include the alternative’s payroll, HRIS, and benefits services, as well as platform setup, internal labor, and payroll cleanup. The cost of staying deserves equal attention. A recurring excess cost can outweigh a transition expense, but that conclusion must come from the fully scoped comparison.
When the CFO asks “is this the cost, or the cover charge?”, the answer is direct. The admin fee is the cover charge. The arrangement earns its keep if its services justify the total cost.