ICHRA vs. Group Health Plan for Remote-First Tech Teams
Individual plans let remote workers pick coverage that actually works in their state.
A 35-person tech company with engineers in four states gets its group renewal and discovers that two remote employees are effectively uncovered by the PPO network their colleagues rely on. The mismatch between plan and workforce appears at renewal, when a plan built for one market meets a workforce that no longer lives in it. Traditional group health plans centralize carrier selection, plan design, and network access for an entire workforce, an arrangement that works cleanly when everyone lives near headquarters and sees the same regional doctors. The moment a company hires outside that radius, the model starts to strain.
The failure is structural. An HMO or a regional PPO that covers employees well in one state may not even be sold in the state where a remote hire lives, and where it is sold, it may offer only out-of-network coverage there. Insurance regulation compounds the problem: mandated benefits, carrier pricing, and plan availability all vary by state, so a plan built around a headquarters market can be mismatched for employees sitting two or three states away before the ink on the renewal is dry. None of the usual levers fix this. An employer can change plan design, shift employee contributions, or switch carriers at renewal, and each of those moves manages cost. None of them extends a network into a state where that network was never sold.
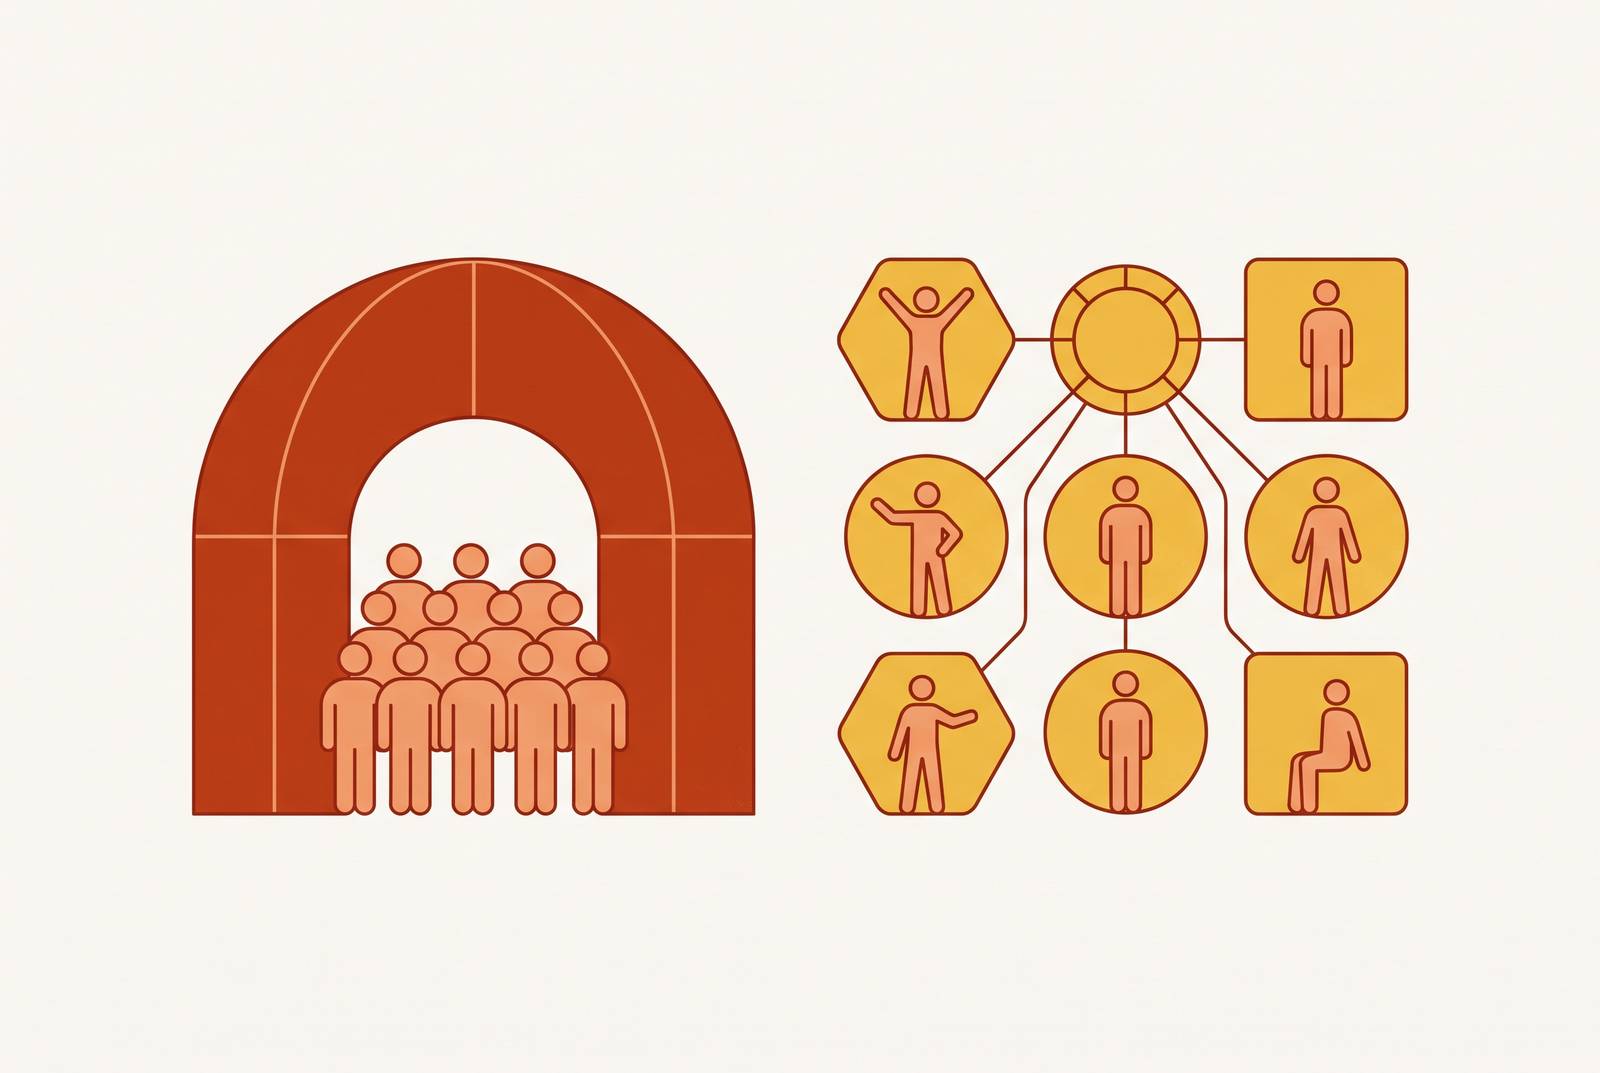
An Individual Coverage Health Reimbursement Arrangement separates two decisions that a group plan bundles together: how much the employer pays, and which insurance the employee actually has. That separation is what makes ICHRA geography-neutral, not as a side benefit, but as the design principle the whole model runs on. The employer sets a defined monthly reimbursement allowance, and eligible employees use it to enroll in any qualifying individual health insurance plan sold where they live, then submit their premiums for reimbursement.
The employer's dollars travel with the person. No one is stuck trying to make a plan built for one region work in another.
ICHRA has been available to employers since January 1, 2020, and CMS now refers to the same arrangement as a CHOICE Arrangement. The rules underneath it are built so eligibility and participation work differently than they do for group plans. There are no minimum participation requirements, a sharp contrast with traditional group plans that commonly need a majority of eligible employees to enroll before a carrier will even issue the policy. There's no employer-size restriction either, so the model works as well for a small startup as it does for a much larger company.
Employers can also vary the reimbursement allowance by employee class, including by geography. A company can calibrate its contribution to local premium costs without having to stand up a separate group plan in every state it hires in. The coverage itself belongs to the employee. It's an individual policy, portable, and it follows the employee out the door if they leave the company, something a group plan structurally cannot offer, since group coverage ends the moment employment does.
When a traditional group plan still fits better than ICHRA
None of this makes ICHRA the correct answer for every team. Group health insurance remains the stronger structural fit for a workforce that is geographically concentrated, reasonably stable, and willing to let the employer own the benefits decision.
When a company's staff clusters in one metro area or one state, a well-chosen group plan paired with a strong regional carrier delivers network depth, employer-level negotiating leverage, and enrollment simplicity that an ICHRA reimbursement budget can't replicate. Group plans centralize the decision-making load in a way that genuinely helps a lot of employees: the employer picks the plan menu, employees choose from a short list, and the carrier manages the network behind it. Employees carry less shopping burden under that arrangement, and less personal risk if they pick poorly, since the plans on offer have already been vetted.
Network lock-in matters here too. Under ICHRA, each employee chooses independently, which can fragment what would otherwise be a shared, collective benefit. And for a company whose current group plan is performing well on claims experience and renewal pricing, switching to ICHRA brings administrative transition costs and a disruption to the employee experience that isn't always worth absorbing.
The sharpest argument against ICHRA is a cost argument. Individual-market plans often carry narrower networks, HMO and EPO structures are common there, and in some markets they cost more per premium than a well-negotiated group plan would. In those markets, group coverage is the cheaper choice at the employee level, and that fact alone should weigh heavily on any company operating in a single, well-served metro area.
The five criteria that determine which model fits a given team
The ICHRA-versus-group-plan decision comes down to five testable criteria: geography spread, budget predictability, employee decision capacity, class-design need, and compliance overhead.
Geography spread is the simplest to check: count the states employees actually live in, then check whether a single group plan's network reaches all of them with in-network coverage. If it doesn't, that's the core failure mode described above, already in motion.
Budget predictability runs in opposite directions under the two models. With a group plan, the carrier resets the premium at renewal based on the prior year's claims experience and current market conditions, which leaves the employer reacting to a number it didn't set. With ICHRA, the employer sets the reimbursement allowance in advance and knows its total contribution exposure before the plan year even starts. For a fast-growing startup adding headcount quarter to quarter, knowing the per-employee benefits cost before a new hire's start date carries real financial planning value.
Employee decision capacity cuts the other way. ICHRA transfers plan selection onto employees, an advantage for people who are confident navigating health insurance on their own and a real burden for people who aren't. Tech workers are often comfortable researching plan options, but that comfort shouldn't be assumed across an entire team. The quality of the employee experience under ICHRA depends on the quality of enrollment guidance, ongoing communication, and reimbursement support the employer builds around it, not on the arrangement itself.
Class-design need is where a lot of companies find their actual answer sits in the middle. Employers can offer a group plan to one class of employees and an ICHRA to another, group coverage for headquarters staff and ICHRA for remote or out-of-state employees, as long as the class structure is maintained correctly. What an employer cannot do is offer both to the same class of employees. Up to 11 employee classes with distinct allowances are permitted, and class-size minimums apply in certain designs when a company maintains a group plan alongside an ICHRA. That's a compliance detail that calls for professional setup rather than a do-it-yourself read of the regulation, and it's often the detail that makes a hybrid model, group coverage at headquarters, ICHRA everywhere else, the practical answer for a team that has a concentrated core and a distributed tail.
Compliance overhead closes out the list, and it deserves its own full treatment, because it's where remote-first teams tend to underestimate what ICHRA actually requires of them.
What ICHRA compliance requires
ICHRA is a formal group health plan under federal law, not an informal reimbursement workaround, and remote-first teams that treat it as a lighter-touch alternative to group coverage tend to learn the compliance requirements the hard way.
The transition notice is the first trip point. Employers must give eligible employees written notice about the ICHRA far enough ahead of the plan year's start, laying out its terms, the monthly allowance amount, and how accepting the offer affects eligibility for ACA premium tax credits. An employee who misses that notice can't make an informed choice between using the ICHRA allowance and claiming the ACA credit instead, since the two are mutually exclusive.
Companies that reach 50 or more full-time-equivalent employees face the ACA's employer mandate, and a properly structured, affordable ICHRA offer can satisfy that employer shared responsibility requirement. Affordability has to be calculated correctly using the relevant safe harbor though, or the employer stays exposed to penalties despite having offered coverage in good faith.
Coverage substantiation is a quieter requirement with real teeth: employers must verify that employees are actually enrolled in qualifying individual health insurance before reimbursing their premiums. An ICHRA that reimburses without that verification step is out of compliance no matter how well the allowance itself is structured.
Remote teams carry an additional layer most group-plan employers never have to think about. Missing a single notice deadline or filing in any one of those states can trigger real penalties. The compliance and network-geography problem is fundamentally jurisdictional rather than just a matter of plan design: mandated benefits, coverage rules, and carrier availability all shift from state to state, and that complexity compounds as a workforce spreads across more of them. Spine's compliance automation is built around exactly this kind of state-by-state variation, tracking the notice timing, class structure, and substantiation requirements that change depending on where an employee actually lives.
This creates an upside that most operators miss. As of 2026, Indiana, Connecticut, and Mississippi offer tax credits to small employers adopting an ICHRA, a benefit most companies in those states don't know to claim.
Modeling the cost comparison, including what group plans hide at renewal
An honest comparison between ICHRA and a group plan has to model the employer's sustainable contribution, the employee's likely out-of-pocket burden, local plan availability, and renewal risk all together. Comparing this year's group premium against a proposed ICHRA allowance figure in isolation misses most of what actually determines which model costs less over time.
Group plans hide risk inside a number that looks stable until it isn't. The carrier prices the plan based on the workforce's claims experience and demographics, and a single bad claims year can push the renewal up sharply, leaving the employer with limited leverage once that renewal lands. Budget predictability looks strong during a good year and weak the moment claims turn against the group.
ICHRA hides a different kind of risk that sits with the employee. The employer's contribution is fixed, but the employee's out-of-pocket cost is not: individual-market premiums vary by age, location, household circumstances, and the specific plan chosen. An allowance that comfortably covers a 28-year-old single employee in one state may fall well short for a 52-year-old with dependents in another, even though the employer's dollar figure never changed.
A genuinely useful comparison runs on five inputs: the employer's sustainable per-employee contribution, the employee's likely total cost under each model, plan availability in each employee's actual location, the employer's tolerance for renewal risk, and the administrative cost of running each model correctly. Because ICHRA shifts plan selection onto the employee while the employer holds a fixed contribution, the model is inherently portable: each person enrolls in coverage suited to their own market without the company needing to stand up separate plan structures state by state. That portability also functions as a compliance asset, since it moves the question of network fit from an employer-level decision to an individual one, which lines up naturally with how much coverage availability and pricing already shift from state to state.
Geography belongs in the cost model as its own variable, not an afterthought. Individual-market premiums can differ substantially from one state to the next, so a reimbursement strategy that's well-balanced in one region may be badly mismatched in another. A company with employees spread across a dozen states needs to model local market rates directly rather than lean on a national average that describes none of them precisely. When weighing the five criteria, geography spread and budget predictability in particular, it helps to separate the benefits decision from the renewal calendar altogether: setting a contribution strategy and leaving plan selection to employees decouples the employer's annual benefits planning from the operational weight of managing multiple group renewals across different states and carriers at once.