Twelve States Twelve Rule Sets One Benefits Platform That Keeps Up Automatically
Continuous monitoring eliminates gaps from manual multi-state compliance reviews.
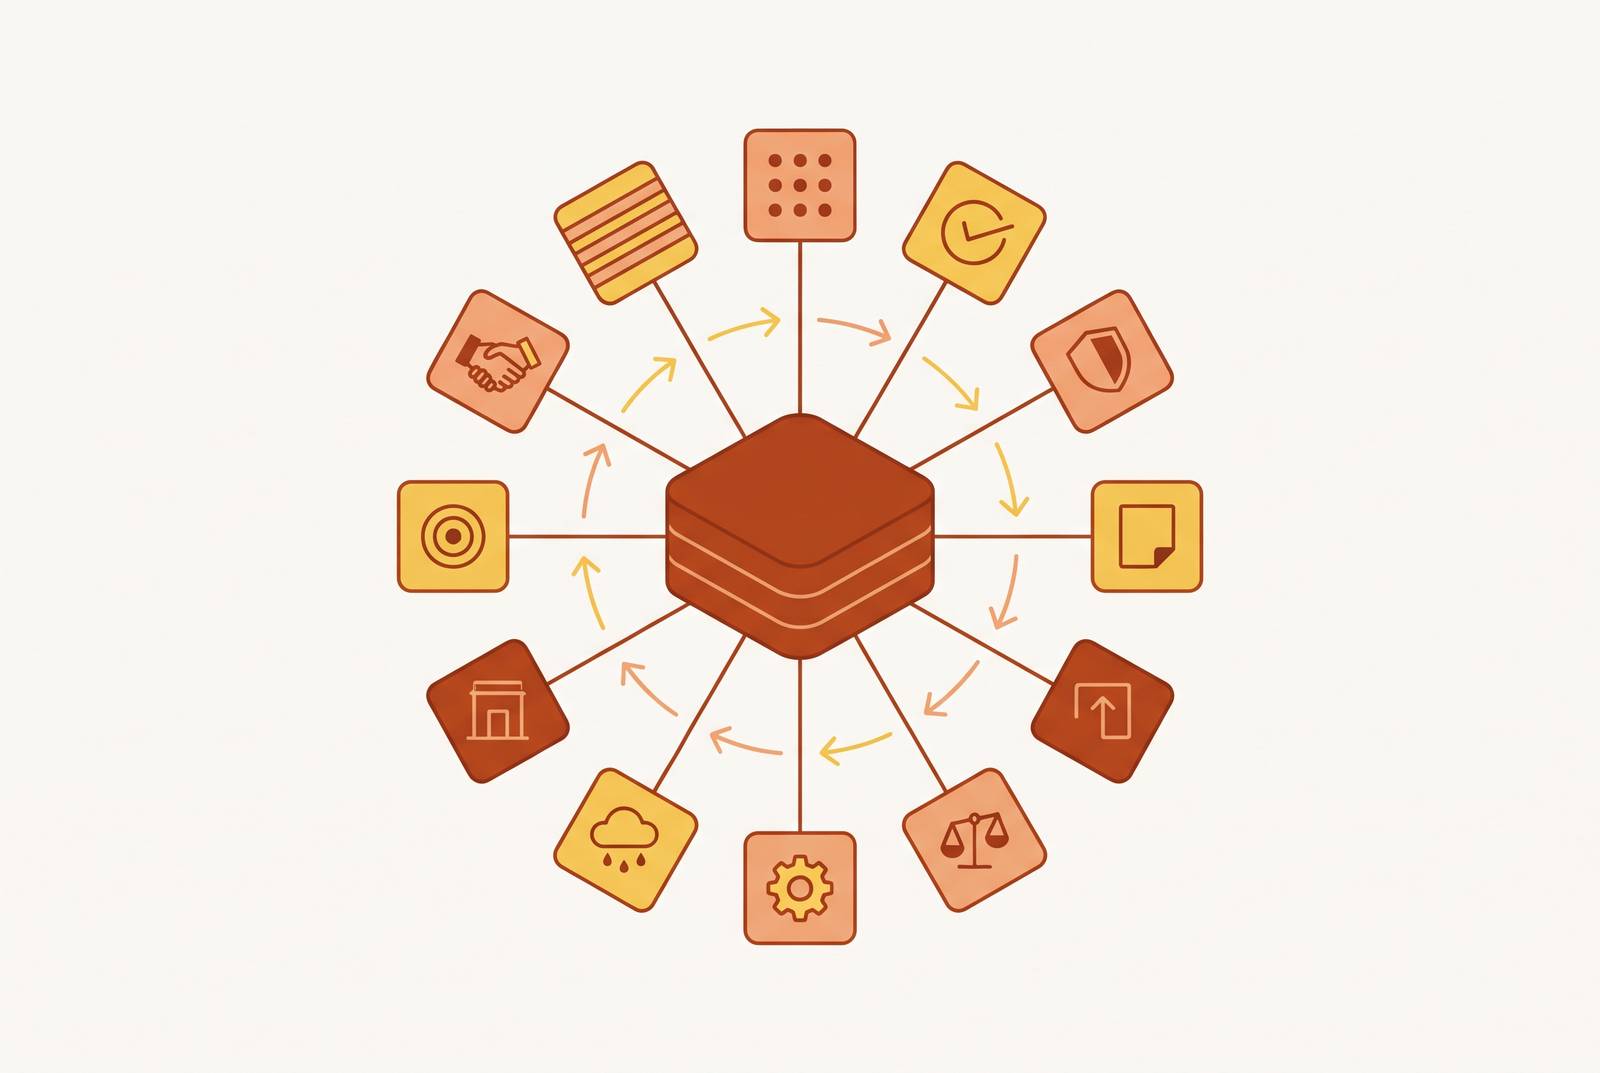
Automated benefits compliance monitoring for a multi-jurisdiction workforce needs a platform that applies each jurisdiction’s rule changes as they happen to shared payroll, eligibility, and enrollment data. For a distributed tech company with employees across twelve states, checking from time to time cannot reliably keep up as rules change and employees move. The durable solution is continuous monitoring that connects payroll and benefits obligations while reserving plan design, negotiation, and HR strategy for human judgment.
Why multi-state payroll compliance broke down for distributed tech companies
A remote engineer relocates to Colorado without payroll learning about the move. A salesperson visits a client in Georgia for two days. A new hire accepts an offer in one state and moves before starting work. Each of these events can leave the employer with obligations that its payroll setup does not cover. The company’s hiring records may look settled while its jurisdictional exposure has already changed.
The mechanism behind that exposure is nexus. An employee performing work in a state, even briefly, can give that state authority to require employer tax registration, withholding, and filing. Multi-state payroll can begin well before a company grows into a large enterprise. Hiring beyond its home state is enough to create the problem, and the relevant location is where work occurs.
A record that stays the same cannot tell payroll how much to withhold when employees work remotely or across state lines. State revenue and labor agencies use information shared between states, federal tax filings, and other signals to identify unregistered employers. The assumption that a single remote employee will remain unnoticed is not a viable operating model.
What "twelve rule sets" actually means in practice across a distributed workforce
Twelve states do not represent twelve copies of one rulebook. Each state governs its own income tax brackets, or absence of income tax, unemployment insurance wage base and contribution rate, paid leave structure, workers’ compensation regime, and filing schedule. Those variables do not move together. An employer must follow each state system that applies to the employee while also meeting federal obligations and any local requirements that apply.
Pennsylvania has thousands of local tax jurisdictions, while Ohio has hundreds of municipalities with their own income taxes. Philadelphia and New York impose local payroll levies calculated separately from state withholding. Yet city-level obligations are not interchangeable. San Francisco replaced its employee payroll tax with a Gross Receipts Tax in 2012, and its remaining payroll-related levies are employer-side business taxes.
The Ohio Department of Taxation identifies reciprocity agreements with Indiana, Kentucky, Michigan, Pennsylvania, and West Virginia. An employee living in one of those states and working in Ohio can claim an exemption from Ohio withholding, but the employer must recognize that particular state combination. Some states also apply the “convenience of the employer” rule, taxing remote employees as though they worked in the employer’s home-office state when remote work reflects personal convenience.
Year-end reporting must reconcile all of these distinctions. Each employee needs one accurate W-2 that reflects the jurisdictions active during the year, despite their different withholding, unemployment, and filing rules. Consolidation requires the employer to preserve those differences accurately enough throughout the year to produce a coherent final record.
Why the complexity does not stay constant — rules change mid-year across jurisdictions independently
A correct configuration is only correct for the rules and employee locations it reflects. State legislatures pass changes that take effect January 1, but agencies also change rates, rules, and filing requirements mid-year. There is no coordinated schedule across jurisdictions. A completed review establishes a point-in-time position.
Benefits obligations introduce another set of clocks. ACA affordability percentages, HSA contribution limits, out-of-pocket maximums, and ERISA filing obligations follow annual cycles that do not align with every state payroll change. An annual benefits review cannot cover every payroll rule, and a payroll update cannot show that the employer is up to date on its benefits obligations. The gap is temporal as well as geographic. Different requirements become actionable at different times, even when they affect the same employees.
State agencies require substantial processing time. Compliance advisors therefore recommend beginning registration well before the first payroll in a new state. Discovering a new obligation at payroll preparation may already leave too little time. Meanwhile, states are increasing audits and using AI to detect payroll inconsistencies. The interval between an operational change and its recognition becomes a source of exposure, even when the next scheduled review would eventually find it.
Why manual tracking and periodic review are structurally guaranteed to produce gaps
A capable payroll team and a disciplined review process do not eliminate the mismatch between continuous change and periodic inspection. Quarterly review operates on a 90-day lag where rules can change monthly. More frequent review shortens the interval but leaves the same dependency intact. Someone must still find each change that affects the employer, work out what it calls for, and put it in place before the payroll or filing it affects.
A tool can calculate a paycheck correctly for every state already configured without recognizing that a new hire has introduced an unregistered jurisdiction. In a manual process, a person must notice the location, understand the nexus implication, and initiate registration before first payroll. The arithmetic may be right while the coverage is incomplete.
When an employee moves from a no-income-tax state to a state with complex local withholding, a system waiting for a manual update continues applying the old rules. Every intervening paycheck can contain incorrect withholding. Real-time location data is therefore a prerequisite for the compliance chain. The structural failure is reliance on human review to synchronize changing locations, changing rules, and separate deadlines.
What continuous automated compliance monitoring actually does — and what it does not replace
Continuous monitoring applies each jurisdiction’s rules in the background, so people no longer have to research them over and over. It centralizes payroll data across states and EINs, applies tax code and withholding updates as they are issued, and detects filing deadline mismatches before filings become late. It also flags potential new nexus when employee location data changes. That flag connects an operational event to a compliance obligation without waiting for a scheduled review to discover it.
The distinction is between awareness and execution. A platform that reports a tax change but waits for a person to implement it leaves a manual dependency in place. Continuous automation applies the relevant update and supports generating and validating year-end forms across active jurisdictions. Built-in error-prevention and audit tools identify discrepancies before they accumulate into year-end corrections. The objective is accurate running data, rather than a concentrated repair effort at filing time.
ACA affordability thresholds, COBRA notice timing, Form 5500 filing windows, and SPD distribution obligations require active tracking against employer-specific eligibility and enrollment data. Monitoring a regulation without connecting it to the employer’s records is incomplete. The platform must relate the obligation to the workforce it governs so that payroll and benefits do not maintain separate versions of compliance status.
Human judgment still has a distinct role. Automation does not determine which plans best serve a workforce, negotiate with carriers, decide when a PEO exit makes financial sense, or provide the employee-facing support that helps people use their benefits. Its value is coverage at scale. High-volume monitoring can expand with the workforce without requiring human review time to increase at the same rate, leaving decisions about benefits strategy with the people responsible for them.
The benefits compliance layer that sits on top of payroll — and why it multiplies the gap risk
Benefits obligations draw on the same employee data as payroll but have different deadlines and penalties. A termination or reduction in hours can affect payroll while also creating a COBRA qualifying event. Divorce and dependent children aging out can create qualifying events as well. These events occur asynchronously across a distributed workforce. A separate benefits process that depends on HR noticing each event and generating a notice introduces another opportunity for an operational change to go unrecognized.
COBRA exposure makes that separation consequential. Employers above a certain size must offer continuation coverage after qualifying events and send notice within a strict time limit. If they fail to do so, they can face per-day penalties and lawsuits. Notice generation, election tracking, and premium collection therefore need a tight connection to eligibility and enrollment data. A payroll event that does not trigger the relevant benefits workflow leaves the employer managing two incomplete views of the same change.
Documentation creates a different kind of gap. A carrier’s certificate of coverage does not satisfy ERISA’s Summary Plan Description requirement, and employers without a compliant SPD face per-day fines per participant and potential legal challenges. Enrollment alone does not establish documentation compliance. Active monitoring must account for the obligation to distribute the required material, rather than treating access to coverage as evidence that the employer has completed every associated duty.
Annual plan requirements add further dependencies. IRS guidance sets ACA affordability percentages, HSA contribution limits, and HDHP minimum deductibles each year, while HHS (CMS) guidance sets annual out-of-pocket maximums for essential health benefits. These affect employee charges and qualifying plan designs, with affordability requirements applied at renewal. DOL also makes cybersecurity, mental health and substance use disorder benefits parity, surprise billing compliance, and benefit distribution integrity priorities when it enforces the rules.
How should tech companies evaluate a compliance platform across a dozen states?
A tech company choosing a platform should check whether it offers continuous monitoring or sends updates from time to time for someone to apply by hand. The first requirement is location integration. The platform must capture where employees actually work, rather than relying solely on permanent addresses, so relocations and hybrid work are visible to its compliance engine. Without that input, even an up-to-date rule library can apply the wrong jurisdiction’s rules.
The next requirement is automated jurisdictional application. Tax code, rate, and filing requirement changes must be applied automatically as they are issued. A claim of multi-state support is insufficient if the platform cannot handle the city, county, and municipal obligations relevant to the workforce.
Payroll and benefits integration should be evaluated by their shared data. COBRA notice triggers, ACA affordability calculations, and Form 5500 preparation must draw from the eligibility and enrollment records that drive payroll. Separate modules connected through manual transfers retain the same synchronization problem as separate systems. Proactive audit tooling should also identify discrepancies, including mismatches between withholding amounts and reported wages, before filing deadlines and any automated state audit notice.
The compliance layer should work with the company’s existing HRIS rather than require a system migration, since replacing established tools creates a switching cost that can postpone coverage. For a company that has outgrown a PEO or relies on a traditional broker relationship, the decisive question is what the existing fees actually buy. The standard is monitoring that applies changes, connects employee events to obligations, and detects discrepancies continuously, rather than periodic review presented as infrastructure.