Fully Insured vs. Level-Funded vs. Self-Insured Health Plans for Mid-Size Startups
How each funding model shifts risk, cost, and control as you grow.
Choosing between fully insured, level-funded, and self-insured health plans is a mid-size startup’s highest-leverage benefits decision because it determines cost exposure, claims data access, and plan flexibility together. Fully insured transfers claims risk to a carrier, level-funded combines fixed payments with potential surplus refunds, and self-funded offers greater control with variable cash flow. The right choice changes as headcount and claims history grow.
Why the funding structure decision matters more than any other benefits choice
The renewal letter arrives with a higher premium, and the immediate response is to shop carriers. That response addresses price within an existing structure. The structure’s continued fit with the workforce, cash reserves, and operating capacity of the company matters more. Carrier selection, deductibles, and HSA funding all operate within limits the funding model has already set.
Those limits extend beyond the next premium payment. They govern the employer’s access to money from favorable claims, visibility into the data behind its renewal, and freedom to change coverage. Forecasts project employer health-benefit costs rising meaningfully in 2026, pushing average total cost per employee to a new high. Against that pressure, defaulting to fully insured can mean paying a risk premium that no longer matches the company’s risk profile.
How the three funding models actually work and what each one trades away
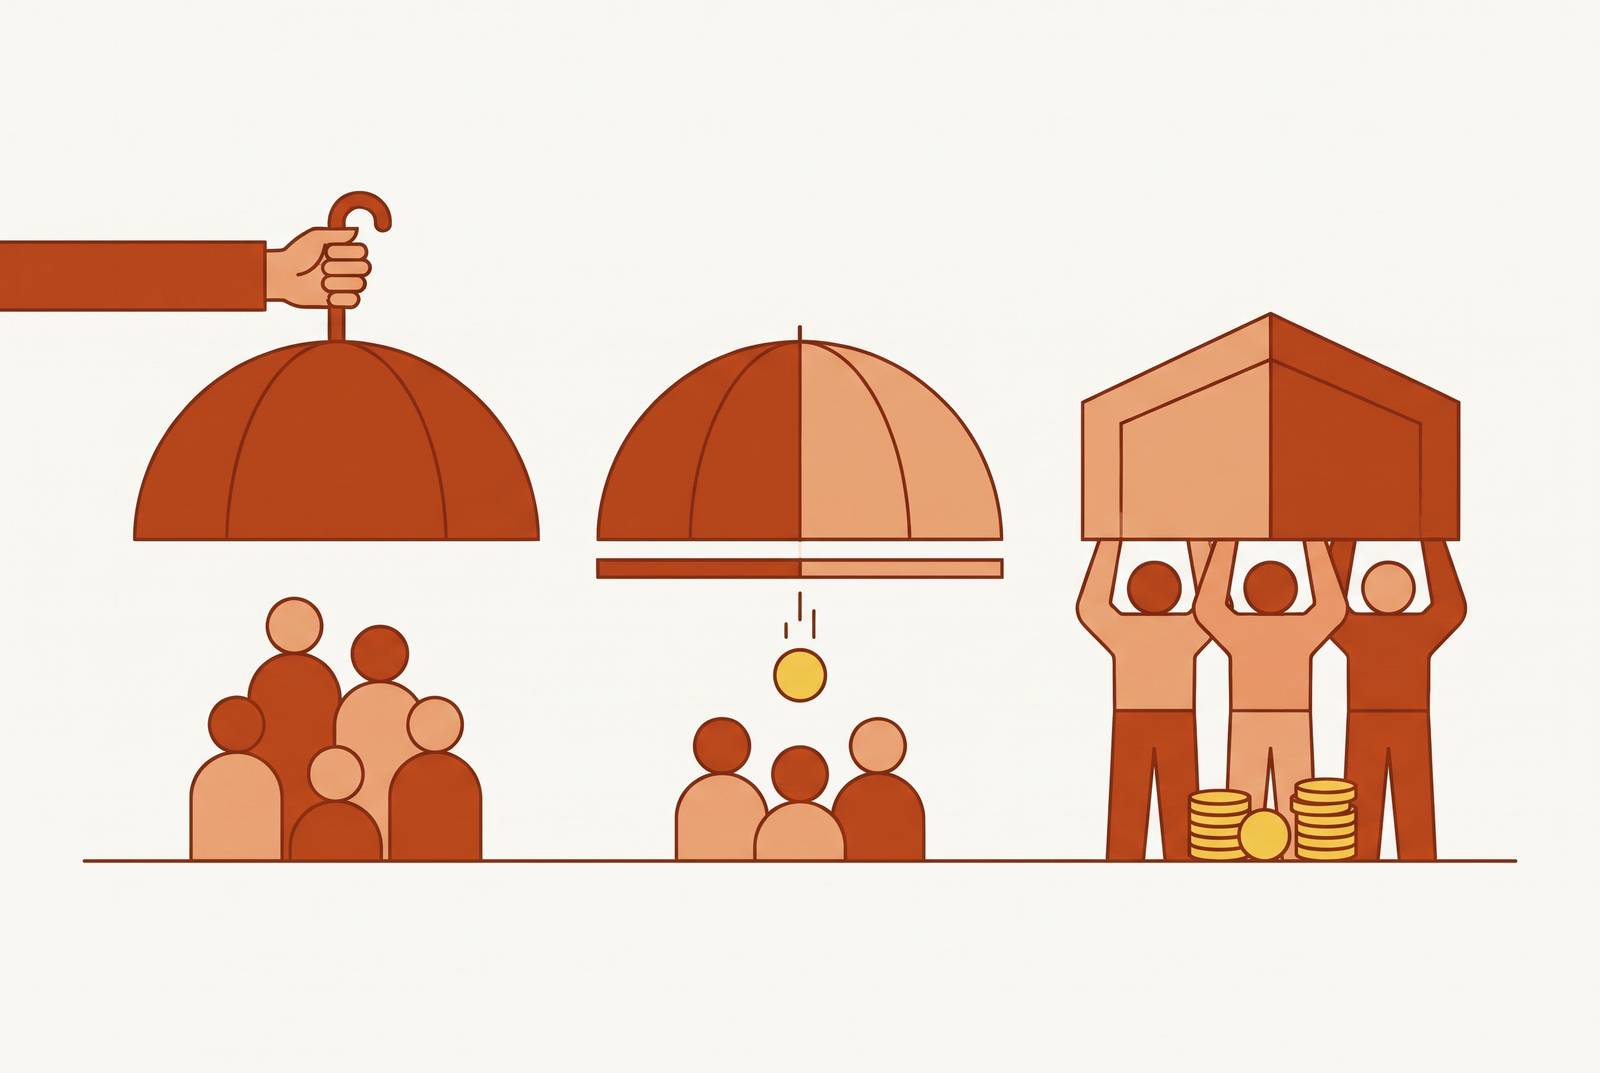
Fully insured places claims risk with the carrier. The employer pays a fixed monthly premium, and the carrier assumes responsibility for claims. If the workforce has a healthy year, the carrier keeps premiums left over after costs. Administration is relatively simple, but plan design stays within the carrier’s filed products and claims data access is limited, particularly for smaller groups. The employer buys predictability at the expense of upside and visibility.
Level-funded is legally self-funded but uses fixed monthly payments. Each payment covers a claims fund, stop-loss insurance, and administrative fees. When claims finish below the projected fund, the employer typically receives a surplus refund or credit, while stop-loss absorbs covered overages when claims run high. Monthly claims reporting gives the employer more visibility than fully insured coverage, and plan flexibility is moderate. The trade is low-to-moderate administrative complexity and employer compliance obligations rather than a complete transfer of responsibility to the carrier.
Self-funded, also called self-insured, gives the employer more control. The employer funds claims as they occur through a third-party administrator, or TPA, and purchases stop-loss insurance to limit exposure. It retains unused claims funds, receives granular claims data, and can design coverage within federal rules independently of a carrier’s product menu. Monthly costs consist of claims funding, TPA or administrative-services-only fees, stop-loss premiums, and plan fees covering obligations such as reporting and filing preparation. Claims funding is the largest component and creates cash-flow variability.
Stop-loss provides two distinct forms of protection. Specific stop-loss caps what the employer can owe for an individual member, while aggregate stop-loss caps total plan claims at a set level above expected claims. Both level-funded and self-funded arrangements operate under ERISA federal preemption, rather than the state insurance framework governing fully insured coverage. That allows a self-funded employer to use a uniform plan design across states, largely free of state benefit mandates and state premium taxes. It also places more of the work of managing the plan with the employer.
What the cost math looks like across the three models for a company in the 50–150 employee range
For a startup with 50–150 employees, level-funded and self-funded arrangements typically have lower expected annual costs than fully insured coverage. Expected cost is not a guaranteed outcome. The comparison depends on actual claims, stop-loss pricing, administrative fees, and the terms governing any surplus return. A favorable claims year widens the economic advantage of alternative funding, while stop-loss bounds the downside.
The fully insured calculation begins with the fixed premium. Lower claims do not reduce that year’s employer payment, because the carrier retains the benefit of favorable experience. A level-funded comparison instead distinguishes the scheduled annual payments from the eventual cost after any surplus refund or credit. Self-funded cost reflects actual claims plus administration, stop-loss, and plan fees.
The surplus mechanism returns money to the operating budget. Under level funding, favorable experience can produce a refund that would have remained with the carrier under fully insured coverage. The state premium tax exemption also creates a structural reduction for level-funded and self-funded plans that does not depend on a healthy claims year. Neither feature alone establishes which alternative will cost less for a particular company. The comparison should look separately at expected cost, worst-case exposure, and what happens when claims are low.
CMS explains that ACA adjusted community rating prohibits using health status to set small-group premiums. For groups under 50, this means a healthy workforce cannot get fully insured pricing based on its own good health. Risk is spread across the insurer’s small-group book. As healthier employers move to medically underwritten alternatives, the remaining fully insured pool can concentrate higher risk and face higher prices.
How headcount and claims history determine which model is the right fit at each growth stage
At smaller headcounts, the decision often prioritizes predictability and administrative capacity over maximum plan control. Fully insured has a fixed premium and is fairly simple to administer. Level-funded becomes relevant when the employer wants predictable payments without surrendering all the benefit of favorable claims. It provides a bridge into alternative funding. That bridge also starts building the claims history the employer needs to make a better-informed choice later.
As the workforce grows, the question shifts toward whether greater control justifies funding claims directly. A larger employer with adequate reserves and administrative support has more reason to consider self-funding than a smaller company without those resources. Headcount alone does not settle the choice. A company with two years of stable, favorable level-funded utilization has a stronger negotiating position with stop-loss carriers than one entering self-funding without its own claims record.
Medical underwriting creates another distinction between the models. Unlike ACA community-rated fully insured coverage, level-funded and self-funded arrangements can be priced on the workforce’s own experience. A young, healthy workforce may benefit from that difference, but workforce characteristics do not remove the need to assess financial exposure. Specific and aggregate stop-loss together put a cap on what the employer could owe for claims, giving it a defined worst-case exposure. The company still needs to assess its ability to support the cash-flow pattern and operational commitments of the arrangement.
That makes growth-stage fit a moving target. A company may first want the simplicity of fully insured, then use level funding to get data and a chance to save, and later consider self-funding for more control. This is an optional progression. The next renewal should reflect the company’s current workforce and evidence, rather than preserve a choice made when both were different.
Compliance obligations that change when a startup moves off a fully insured plan
With alternative funding, the employer takes on much more of the compliance work. The plan sponsor bears ERISA fiduciary responsibilities, including maintaining a written plan document, distributing a Summary Plan Description, and providing compliant claims-and-appeals procedures. Required notices include the Summary of Benefits and Coverage, COBRA notices, and HIPAA privacy notices. The employer still has those responsibilities even when a level-funded package is easy to administer.
Form 5500 is a common point of confusion. For calendar-year plans subject to filing, the prior year’s return is generally due by mid-summer, with an extension of up to two and a half months available. The employer should not assume that its carrier, TPA, or advisor has completed the filing unless responsibility has been confirmed in writing. The plan sponsor also pays the PCORI fee on IRS Form 720 by July 31 of the following year, using the annually set rate per covered life. The sponsor must also handle gag-clause attestations, broker and consultant compensation disclosures, and prescription drug and health care spending reporting.
Private employers above the federal COBRA size threshold must offer continuation coverage, but employers below that threshold may lose access to continuation when moving to level funding. Most state continuation laws apply only to fully insured plans. Leaving that framework can therefore create a gap. This is distinct from nondiscrimination testing, which prevents self-insured medical plans from favoring highly compensated individuals in eligibility or benefits and can make their excess reimbursements taxable if the plan fails.
Coverage flexibility also changes what the employer must evaluate. Fenwick & West explains that level-funded plans are not subject to ACA mandates on essential benefits. A lower price can therefore reflect narrower coverage as well as a different way of financing the same benefits. Applied behavior analysis for autism and specialty drug exclusions are documented gaps in self-funded and level-funded plans. The economic comparison must account for those coverage differences rather than treating every proposal as interchangeable.
Hiring an employee in a new state triggers income tax withholding registration, unemployment insurance registration, workers’ compensation coverage, and applicable paid-leave obligations. These requirements apply regardless of the funding model. ERISA preemption allows a more uniform health plan, but the employer still has to meet state employment obligations. The employer remains responsible for tracking that separate layer of work.
How the funding model decision intersects with the PEO exit question
A startup leaving a professional employer organization, or PEO, is also choosing how to finance its health plan. Inside the PEO, employees are pooled into large-group fully insured or master self-funded coverage. The individual client company does not choose the funding structure, obtain its own claims data, or customize plan design. Exit changes that relationship. It creates an opportunity for control while exposing the company to its own claims risk without the PEO’s pooling protection.
This makes a per-employee price comparison incomplete on its own. A PEO arrangement and a broker-supported standalone plan differ in who makes the funding decision and what data the employer receives. Health-plan spending then takes the form of fixed premiums, fixed level-funded payments, or variable claims funding, depending on the funding model. The comparison also depends on the underlying plan’s expected claims, risk protection, and coverage.
The transition work depends on the chosen model. A mid-year move to fully insured coverage is relatively straightforward, while level-funded or self-funded coverage requires stop-loss underwriting, TPA contracting, plan documents, and ERISA fiduciary setup. Those steps should begin well before exit. January 1 is the clean exit window, with planning beginning at least six months ahead to align benefit elections and avoid mid-year W-2 and payroll complications. Choosing level funding at that point also starts building a claims record for later stop-loss negotiations, whereas fully insured coverage generally preserves the data limitation.
What to actually evaluate when choosing between the three models at renewal
The practical decision rests on four inputs, which are headcount and growth trajectory, risk tolerance and cash reserves, claims history, and administrative capacity. Each addresses a different constraint on the choice. Growth changes the case for control, while workable variable claims payments require adequate reserves. Claims history informs underwriting, and managing the obligations attached to alternative funding requires adequate administrative capacity.
Cash-flow tolerance deserves attention separate from annual exposure. With self-funding, the employer must pay claims as they occur, even when it has aggregate stop-loss protection. Level funding removes that monthly variability while preserving much of the potential economic upside. For startups with limited runway or close investor scrutiny of cash burn, it is typically the better entry point into alternative funding. Without at least one full plan year of claims data, stop-loss underwriters also price conservatively, weakening the immediate case for self-funding.
The evaluation should compare expected cost, worst-case exposure, and surplus scenarios before the renewal deadline. It should also account for coverage differences and the employer’s ability to manage compliance, rather than letting a lower projected cost decide the result alone. Advisor capability becomes important at this stage. An AI-native brokerage can support the decision by analyzing workforce claims against carrier pricing across all three models, rather than limiting the exercise to the incumbent fully insured renewal. That analysis belongs at every renewal, because the structure that fit at 30 employees may no longer fit at 80.