PEO Cost per Employee Math for Series B Startups
When a PEO stops saving money, it costs you more than you think.
A professional employer organization earns its fee at the beginning of a startup's life and loses the argument for itself somewhere later, and the whole case for or against a PEO comes down to figuring out which side of that line a company currently sits on. The structural divide is simple: a 15-person startup buying insurance on its own sits in the small-group market, where carrier choice is thin and the company absorbs the full swing of its own claims history year over year. A startup folded into a PEO's pool, often 20,000 employees or more, qualifies for large-group PPO plans, smoother annual rate increases, and carrier options that were never on the table when it was negotiating alone. At low headcounts, the medical premium savings alone can exceed the entire PEO administrative fee, which makes the arrangement cost nothing on a net basis for the smallest companies that use it.
The pooled insurance rate is the engine, but it's not the only thing riding on it. A PEO bundles in a 401(k) plan with no separate setup cost, pay-as-you-go workers' comp, and compliance support across multiple states, all as one package, which matters most to a seed-stage team that has no internal HR function to stitch those pieces together on its own. The recruiting case is concrete and immediate: a 10-person startup can offer a new hire an Aetna or Blue Cross PPO option within weeks of signing, turning benefits from a liability in an offer negotiation into something that simply isn't a problem against better-funded competitors.
That's the arrangement at its strongest, and it holds for exactly as long as the company itself cannot replicate that scale on its own. The same forces that make a PEO valuable at 15 employees start working in reverse once headcount and payroll grow large enough that the company could negotiate comparable insurance rates directly. Nothing about the PEO's pricing changes when that happens. What changes is whether the company still needs what it's paying for.
Two pricing models, each hiding a different kind of cost growth
PEOs charge for their services in one of two ways, and the choice a founder makes at signing quietly shapes the company's cost curve for years afterward, often without anyone modeling what happens after the next two hiring rounds. The first model is a flat fee per employee per month. It's easy to budget against, but it doesn't scale with salary, so a junior coordinator and a senior VP of Engineering cost the PEO the same flat fee. As headcount grows, the per-employee rate can tick down slightly at volume tiers, but the total bill still climbs in a straight line with every hire.
The second model prices as a percentage of gross payroll, and it scales automatically, and silently, with every raise, every promotion, every bonus and commission paid out, with no change at all in the services the PEO actually delivers. That distinction becomes expensive at exactly the moment a company starts competing for senior talent. A company whose average salary rises as it matures, which is precisely what happens heading into Series B, pays more every quarter under a percentage model without renegotiating a single term of the contract.
Run the numbers at a mid-sized company averaging $60,000 per employee: the gap between a flat PEPM quote and a percentage-of-payroll quote can add up to a large sum annually, a figure that rarely appears in the sales pitch that got the company into the contract in the first place. Neither model, on its own, captures the full bill. Setup and onboarding fees, year-end W-2 and ACA reporting charges, early termination penalties, and workers' comp true-ups tend to arrive later as separate invoices tied to payroll variance, sitting outside whatever headline rate was quoted.
None of this means the percentage model is a mistake in every case. Percentage-of-payroll pricing often comes bundled with deeper service, more hands-on HR support, more involved compliance work, and for a company with a flatter salary structure that bundling can be worth paying for. This is narrower and more specific: the wrong pricing model for a high-salary, fast-growing Series B company lets the PEO fee grow faster than headcount itself, and that growth compounds at the exact moment the company's payroll is scaling the fastest.
The arithmetic of the crossover tipping point by headcount band
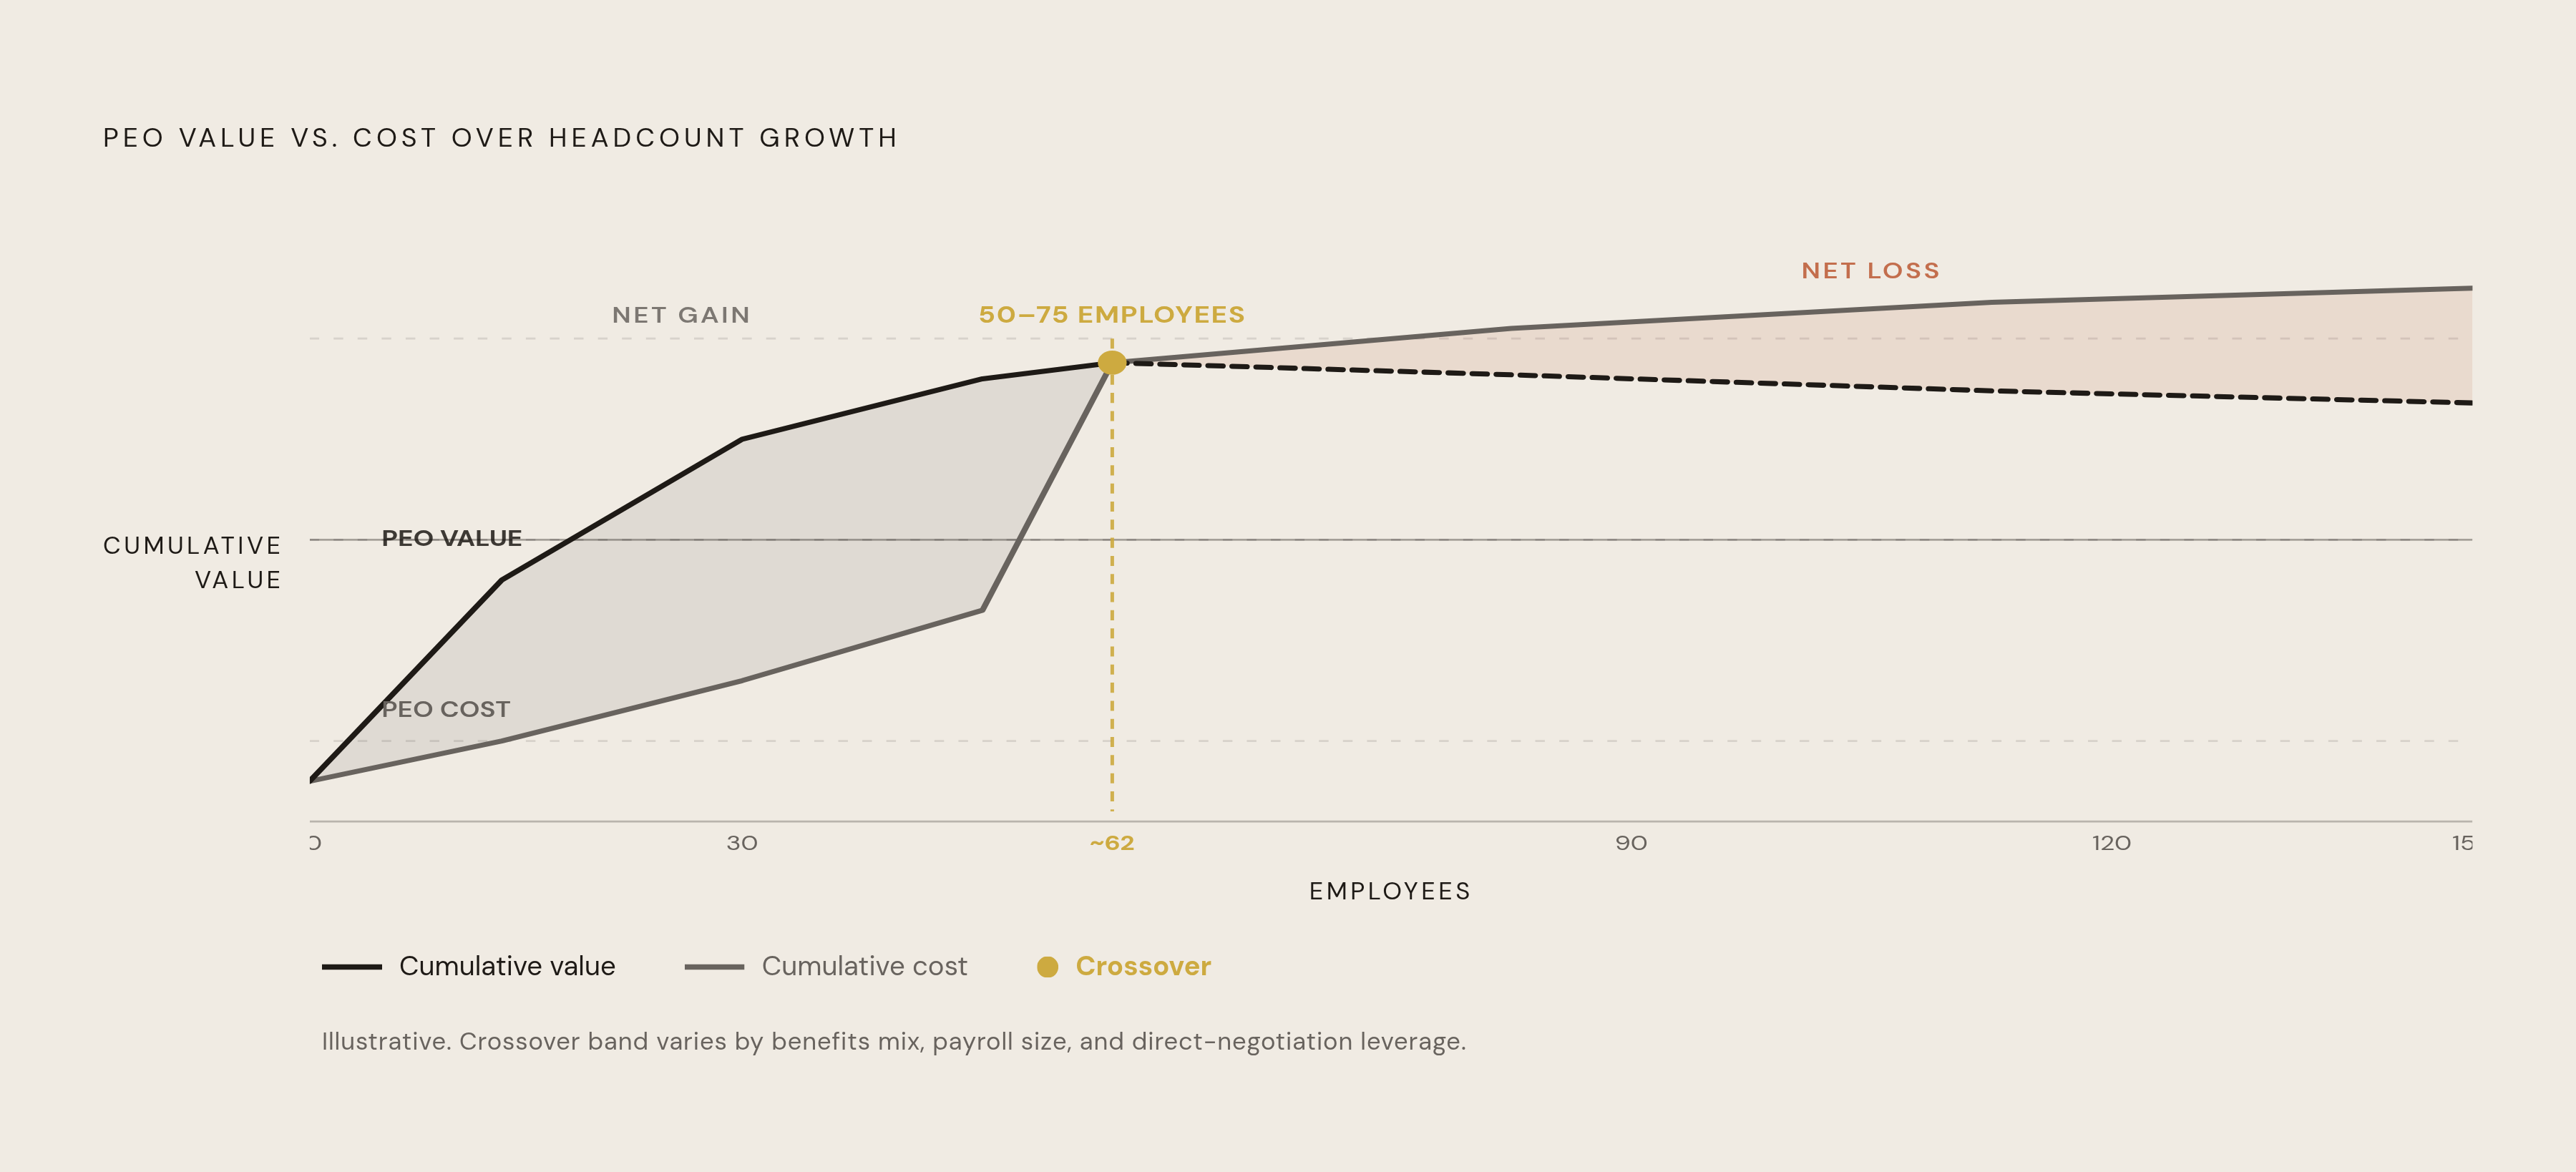
The crossover from net-positive to net-negative PEO economics isn't a matter of opinion or company culture. It falls directly out of the arithmetic laid out above, and it moves depending on which pricing model a company picked, how fast its average salary is climbing, and whether it has grown large enough to replicate large-group insurance access on its own. For most Series B startups, that crossover is somewhere inside a broad band of headcount, not at one fixed number.
Below a certain employee threshold, the math stays favorable. The 50 to 75 employee band is where most tech companies hit the crossover zone. At that size, a company can start negotiating directly with carriers and realistically access large-group rates without a PEO acting as the intermediary. Meanwhile the PEO fee itself, now applied to a larger headcount at a flat PEPM rate or a percentage of a payroll that's grown with it, has grown substantially in absolute dollar terms, without the insurance savings growing at anywhere near the same pace. Past a certain scale, self-administered benefits programs frequently compete just as well as the PEO's offering, because the company's own headcount is now large enough to negotiate comparable rates on its own, and the PEO's pooled buying power stops being a meaningful advantage.
One part of this math gets missed even by companies that are watching their PEO fee closely: the FICA savings tied to pre-tax employee contributions. When employees pay their share of premiums through a Section 125 cafeteria plan, those contributions come out pre-tax, and the employer normally avoids paying FICA on that amount. Under a PEO's co-employment structure, that FICA savings accrues to the PEO instead of the employer. At the crossover headcount, with typical employee premium contributions, that forfeited amount adds up to a meaningful sum every year, and it keeps compounding for as long as the company stays on the PEO.
Percentage-of-payroll pricing speeds up the whole crossover. A Series B company whose average salary rises with every senior hire watches its PEO fee climb in step, with no new service being delivered in exchange. What makes the crossover easy to miss in real time is that it isn't symmetric. The savings that justified signing with a PEO in the first place (insurance access, bundled administration) are front-loaded into the earliest years of the relationship, while the costs that erode the return (fee growth, FICA leakage, the negotiating leverage the company gave up) are back-loaded, building quietly until the full size of the gap becomes obvious.
Series B diligence and the oversized PEO fee
An oversized PEO fee costs more than cash. Once it has crossed into net-negative territory, investors reviewing headcount models during Series B diligence read an inflated people-cost line as a sign the company doesn't have a handle on its own operations. Series B investors look at benefits cost structure as a routine part of headcount modeling, and a PEO fee running materially above what the company could achieve on its own becomes a red line item investors will ask about directly. Co-employment arrangements add a second layer of friction here, since acquirers and underwriters generally want a clean employment structure: one employer of record per employee and a single, clear tax filing history, which a PEO relationship complicates.
Contract timing makes a late discovery far more costly to fix. PEO contracts typically run 12 to 24 months and renew automatically, so a company that realizes mid-contract that it has already crossed the tipping point can't simply walk away. Early termination usually triggers a penalty tied to a meaningful share of the remaining contract value, and that's before counting the cost of standing up replacement payroll and HRIS systems, plus the internal labor hours HR, payroll, finance, and IT all have to spend on the transition. A company that discovers the math has turned against it three months before a raise is in a far weaker position than one that caught it a year earlier.
The practical posture, given all that, is to exit cleanly before raising Series B, or to go into the round with a documented plan to exit within 12 months of closing, because either way the diligence conversation needs to show investors that the company understands its own cost structure and has a plan for it. Investors reading a company's numbers tend to extend that judgment outward. A company that hasn't bothered to benchmark its benefits costs against the market is unlikely to have benchmarked much else.
The true cost of exiting a PEO once the math has already flipped
Leaving a PEO after the math has already turned isn't free, and the cost isn't limited to the termination fee on the contract, but a layered set of transition expenses that compounds the longer a company waits or the less carefully it plans the exit. Contract termination penalties are the most visible piece: early exit commonly costs a company a share of its remaining contract value, and in one illustrative case, a company leaving at month 14 of a 24-month contract owes ten months of fees as a penalty.
That penalty is only the start. Replacing the PEO means standing up payroll and HRIS systems independently, absorbing internal labor hours across HR, payroll, finance, and IT, and onboarding new vendors, all of which carry direct costs that have to be weighed against whatever the company expects to save by leaving. COBRA administration is a smaller but real risk during the transition: once the PEO's system stops handling notifications automatically, COBRA admin costs tend to rise because the process reverts to manual handling, with added exposure to penalties if election notices go out late or get missed entirely.
One detail catches companies off guard at the paycheck level. Employees who already hit their FICA wage base under the PEO's employer identification number will hit it again under the new employer's EIN after the transition, which is a real and noticeable change to employee paychecks that needs to be communicated well before the transition date, not discovered by employees on their first post-exit pay stub. Timing the exit itself matters as much as planning it: the consistent recommendation is to leave on January 1, aligned with the plan year, the carrier renewal date, and the payroll calendar, never in the middle of a year.
None of this is a case for staying put. The exit cost should get modeled as a one-time investment weighed against the annual savings that follow from leaving, and that comparison usually shows that a company which waited two years past its real exit point has already given up more in cumulative overpayment than the exit itself will ever cost. The expensive choice is the delay, not the transition.
The benefits cost picture after a clean exit
A Series B company that times its exit well and builds its own benefits program doesn't take a step down in coverage. It gains access to insurance quality on par with what the PEO offered, more control over plan design, and cost reductions that the PEO's one-size-fits-all menu had been blocking. Plan designs that open up once a company is independent include copay-based structures that remove the high-deductible barrier entirely, reference-based pricing, and primary-care-centered plans, none of which typically appear on a PEO's standardized list of options.
Carrier negotiation itself changes shape after the exit. An AI-native brokerage can model a company's own historical claims data against what carriers are charging, and that analysis can show precisely where a company had been subsidizing the broader PEO pool and where its own risk profile would actually cost less outside it, a level of detail a traditional broker rarely brings to a renewal conversation. That timing lines up with the broader market, too: health benefit costs are projected to rise significantly in 2026, so the renewal cycle right after a PEO exit is the moment to benchmark plan design against the market rather than accept whatever a carrier first proposes.
The Section 125 cafeteria plan savings that had been flowing to the PEO under the co-employment structure now flow back to the employer directly, and for a payroll of 75 or more employees, that recurring annual benefit keeps compounding for every year the company stays independent. Open enrollment itself doesn't need to get worse after leaving a PEO's portal behind. Digital-first enrollment tools, including AI-supported enrollment and mobile interfaces, are now standard among independent plan administrators, so a streamlined employee experience was never something only a PEO could deliver.